How CrowdHive Works · 7 min read
Latin America: where 17% yields come from
Why Latin American businesses pay 17% for capital: high base rates, a huge SME financing gap, nearshoring, cheap hydropower, and the risks behind the yield.
If you have spent any time investing in European crowdlending, a headline rate of 17% per year probably triggers a healthy reflex: is this real, and what is the catch? It is the right question to ask, and it deserves a straight answer. The short version is that 17% is not a marketing number invented by a platform. It is roughly what creditworthy small and mid-sized businesses in parts of Latin America actually pay for capital, because money simply costs more there than it does in Europe. This article explains why, where the demand is coming from, and what risks you take on in exchange for that yield.
Money costs more in Latin America, full stop
Start with central bank rates, the floor under every loan in an economy. As of September 2026, the Central Bank of Brazil holds its benchmark Selic rate at 13.75% per year, after cutting from a peak of 15%. Mexico's central bank, Banxico, holds its overnight target rate at 6.5%. Compare that with the euro area, where the ECB's policy rates have spent most of the past two years in the low single digits.
Now remember that a central bank rate is what the safest borrowers in the system pay, roughly speaking. A small or mid-sized business borrows at the policy rate plus a spread for credit risk, plus the bank's operating costs and margin. When that base-rate floor is already in double digits, as in Brazil, a commercial loan to an SME lands well above that. In Mexico the floor is lower, but bank credit to smaller businesses remains scarce and expensive relative to Europe, so effective borrowing costs for SMEs are significantly higher than European businesses would ever accept.
The second half of the story is access. According to the Inter-American Development Bank and the IFC, the financing gap for smaller businesses in Latin America and the Caribbean runs into the hundreds of billions of dollars, with the large majority of SME financing needs going unmet by the formal banking sector. In practical terms: a profitable, growing company with real contracts and real customers can walk into a bank and still walk out empty-handed, not because it is a bad credit but because local banks concentrate on large corporates and government debt. When banks will not lend, businesses that need capital pay a premium to whoever will.
Put those two facts together and 17% stops looking exotic. It is the market-clearing price for business credit in economies where the base rate is high, banking competition for SME clients is thin, and demand for capital is growing. A European investor sees an unusually high yield. A Mexican or Brazilian entrepreneur sees a normal, sometimes even attractive, cost of funding.
Three engines of demand
High rates alone do not make a loan worth funding. What matters is whether borrowers have real revenue behind them. Three regional trends are generating exactly that kind of demand, and they map directly onto the first project categories on CrowdHive.
Nearshoring is pulling capital into Mexico
As global supply chains reorganize around proximity to the US market, Mexico has become one of the main beneficiaries. Foreign direct investment into Mexico reached a record of roughly 41 billion US dollars by the third quarter of 2025, already surpassing the full-year 2024 figure, with manufacturing taking the largest share. Factories, suppliers and logistics firms are expanding, and every one of them needs working capital, equipment finance and invoice factoring.
This is the backdrop for one of the first loan categories on our platform: a Singapore-based fintech with deep credit-risk and fraud-prevention expertise expanding into Mexico to provide digital lending to consumers and SMEs, including factoring. Its repayment source is the cash generated by its own loan and factoring portfolio, in a market where demand for credit far outstrips bank supply.
Paraguay has some of the cheapest clean power on the planet
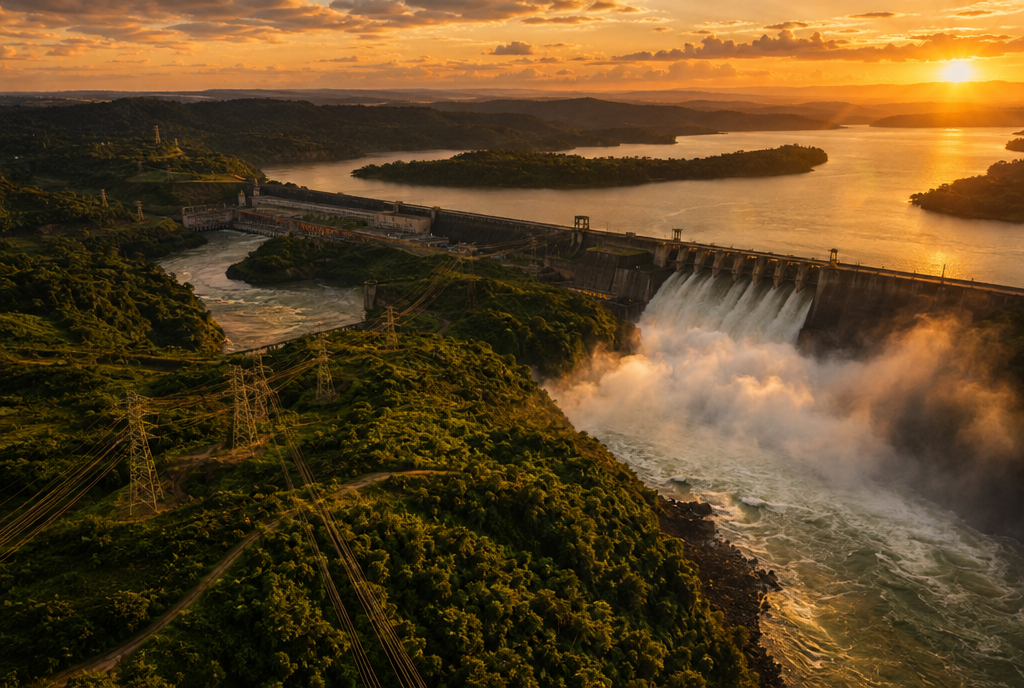
Paraguay is a small economy with an enormous asset: hydropower. The binational Itaipu dam alone supplies the large majority of the country's electricity, with the Yacyreta and Acaray plants covering most of the rest, making Paraguay's grid almost entirely hydroelectric. Paraguay co-owns Itaipu with Brazil and has historically used only a fraction of its share of the output, exporting the surplus.
Abundant, cheap, renewable electricity is precisely what energy-hungry digital infrastructure needs. That is why data center operators and developers of power-ready industrial sites are moving in. Among CrowdHive's first projects are a B2B IT integrator building its own data center near Asuncion, with grid capacity pre-approved by ANDE, the national utility, and a first phase serving existing clients, plus a high-density expansion module aimed at client AI and GPU workloads. A separate developer is preparing a power-ready site in Alto Parana for a specific buyer under a purchase agreement. If you want the bigger picture on why computing infrastructure is being financed with debt everywhere from Virginia to South America, read why the AI boom runs on debt.
Brazil is building the region's digital backbone
Brazil hosts the largest data center market in Latin America, and the buildout is accelerating as cloud and AI demand grows. Construction is done by specialist engineering firms working under contracts with data center operators. One of our first projects funds a Brazilian EPC contractor, an engineering, procurement and construction firm with more than four years of data center experience, delivering a new data hall of roughly 1 MW of IT capacity, including high-density GPU racks, at an operating facility under a signed 5.8 million dollar contract. Repayment comes from the client's milestone payments under that contract, not from speculative future sales.
A European investor sees an unusually high yield. A Mexican or Brazilian entrepreneur sees a normal, sometimes even attractive, cost of funding.
Why this credit flows through platforms, not banks
Across the region, private credit, meaning lending done outside the traditional banking system, is growing fast as investors step into a financing gap that analysts estimate in the hundreds of billions of dollars across infrastructure, energy and mid-market companies. Crowdlending is the retail-accessible end of that same movement. A platform like CrowdHive originates a loan to a business, runs due diligence on ownership, accounts, customers and repayment sources, and then assigns the claims to investors. The loans in this first wave use a bullet structure: monthly interest during the term, principal repaid at maturity. If that structure is new to you, see bullet loans explained.
The honest part: 17% is the price of risk
There is no such thing as a free five extra percentage points. The yield is higher because the risks are higher, and you should name them before investing.
- Currency risk, mitigated but not gone. The loans are denominated in US dollars, so you are not directly exposed to swings in the Mexican peso, Brazilian real or Paraguayan guarani. But the borrowers earn much of their revenue in local currency. A sharp devaluation makes their dollar debt more expensive to service, which turns currency risk into credit risk.
- Country risk. Political shifts, tax changes, capital controls or legal unpredictability can affect a borrower's business or the enforcement of claims. Latin American jurisdictions vary widely, and events like elections or trade disputes can move the ground under a project.
- Credit risk. These are growing businesses, not blue-chip corporates. A contract can be delayed, a client can pay late, a loan portfolio can underperform. Bullet structures concentrate principal repayment at the end of the term, which is exactly when the borrower's plan has to have worked.
This is why the rate is 17% and not 7%. The interest you earn is compensation for bearing these risks, and no structure removes them entirely. What a serious platform can do is underwrite carefully, secure the loans with collateral, and manage recovery centrally if something goes wrong. On CrowdHive, BellaVista acts as Collateral Agent and pursues recovery on behalf of investors. How those layers fit together is covered in how your investment is protected.
So where do 17% yields come from? From real economies where capital is scarce and expensive, from businesses riding genuine structural trends, nearshoring, cheap hydropower, the digital buildout, and from investors willing to be paid for risks that European credit markets rarely offer at any price. Understand the risks, size your positions accordingly, and the number stops being suspicious and starts being what it is: a price.
Investing involves risk, including the possible loss of capital. Past performance is not indicative of future results. BellaVista Invest One AG facilitates lending to businesses and does not provide investment advice.